Home & property claims made easier
Filing a home or property claim doesn't have to be complicated. We're here to guide you step-by-step, so you can get right back on track.

The home & property claim process
Preparation
As long as it is safe to do so, document the damage with photos, notes, and anything else that might be helpful. If possible, take steps to reduce further damage.
File your claim
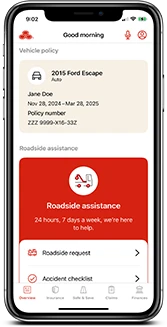
You can file your claim through the State Farm® app or on our website. You can also call us at 800-SF-CLAIM (800-732-5246) to file. We’ll let you know we received your claim.
Assignment
We’ll assign a claim handler (or team) to manage your home or property claim and guide you. They’ll contact you to discuss the damage.
Investigation
Your claim handler will determine if your claim is covered, and estimate the cost of any covered damages. Your claim could be eligible for the State Farm Select ServiceTM Program.
Settlement
If you’re entitled to a settlement, State Farm will pay you or a service provider based on your claim and policy. Payments over your deductible will be issued as quickly as possible. For deductible details, log in to your account.

Questions? No problem. Log in to message your claim handler(s) online or through the State Farm app. Or call us at 800-SF-CLAIM (800-732-5246).
What is and isn’t typically covered under a home & property claim
No two claims are exactly alike. Here’s a list of some of the things that are and are not typically covered by home & property insurance. Check your policy or ask your agent to find out what your policy covers.
- Typically covered: wind, hail, fire, and lightning. This includes roof damage from a downed tree.
- Not typically covered: wear and tear, rot, deterioration, and workmanship (improper installation/repairs).
- Typically covered: losses caused by an abrupt release of water from a pipe inside the home, frozen/burst pipe if reasonable care is used to maintain heat in the home, water backing-up through a sewer or drain (with Back-up of Sewer or Drain endorsement) and water damage to your home caused by ice dams.
- Not typically covered: losses caused by flood, subsurface water, surface water, water backing-up through a sewer or drain (without endorsement), tidal water, tsunami, overflow of a body of water, spray from any of these whether driven by wind or not, frozen and burst pipes if reasonable care to maintain the heat did not occur.
Things to think about before filing a home or property claim
It’s up to you to decide if you want to file a claim. You may have coverage to help with the repair or replacement when covered losses occur.
- Payment for covered damage
- Coverage for temporary living accommodations when a covered loss causes your home to be uninhabitable
- Payment for personal property that’s damaged or stolen by a covered loss
- Liability coverage for covered claims if someone is hurt while visiting your home
Check your policy details for more information.
Here is some information on how to recognize the signs of wind and hail damage.
Here are some of the signs of potential wind or hail damage:
- Shingles in your yard, as well as raised or missing shingles
- Water stains on your highest ceiling
A State Farm representative can explain the difference between normal wear and damage.
Water damage isn’t always easy to spot, but here are some signs you might have a problem:
- Dark or wet-looking spots on your ceiling or walls
- Cracking, bubbling, or flaking paint on drywall
- A puddle that returns after you’ve cleaned it up
- The sound of running or dripping water behind your wall
- A damp, musty or moldy smell
- File your claim online
- Use the State Farm app
- Call 800-SF-CLAIM (800-732-5246) 24/7
Be aware you might need some items to be able to a file a claim, such as date, time, location and details of the incident, property involved and policyholder’s contact information.
Visit Roof Claims to learn how to select a roofing contractor, what’s typically included in a roof repair estimate, and more.
Understand your property’s valuation
Depending on your policy, personal property coverage can be based on the item’s actual cash value or replacement cost.
- Actual cash value is the value of the damaged part of the property at the time of loss. It is defined as replacement cost less depreciation.
- Replacement cost means the cost to repair or replace property with a comparable item.
Review your policy or speak with your agent if you aren’t sure how we cover your personal property.


Your claim could be eligible for the State Farm Select Service program
Select ServiceOr call 800-SF-Claim (800-732-5246), 24/7
Frequently asked questions about home claims
Unless it’s excluded in your policy, a homeowners policy typically covers accidental direct physical loss to your dwelling or other structures, personal liability and medical payments to others.
Homeowners policies also provide personal property coverage for specific incidents, including but not limited to:
- Fire
- Lightning
- Windstorm or hail (when wind or hail causes an opening in a roof or wall and allows rain, snow, sleet, sand, or dust to enter)
- Theft
- Vandalism
- Certain types of abrupt water damage
You can choose to receive your payment via electronic payment options or direct deposit when feasible, or paper check.
Your premium won’t necessarily go up after you file a home & property claim, but it might. It’ll depend on several factors, including the claim details, how much your property will cost to repair or replace, and how many claims you’ve filed in the past. Speak with your agent to determine if your premium is likely to go up because of your claim.
You’ll be responsible for your deductible amount for covered damages up to the limit of your policy. However, your Insurance policy won’t cover any expenses beyond your coverage limits.
It depends on the type of claim and your liability coverage and will need to be determined during the investigation stage of your claim.
You can choose any contractor you like, but if you need help finding a contractor, give our Contractor Locator a try.
If coverage does not apply for a particular claim, we’ll send you a written letter explaining the specific policy language responsible for the denial of your claim.
Visit Simple Insights® to learn more about home inventories, including how to create one.
Yes. In addition to your dwelling, State Farm homeowners insurance covers other structures located on your residence premises separated by clear space from the dwelling. Your policy typically covers other structures at 10% of your dwelling coverage.
This includes, but isn’t limited to:
- Fences
- Detached garages
- Equipment sheds
- Barns
- Guest cottages
- Contact your agent about insuring other structures on your property.
Simple Insights® on home insurance claims
Looking for help protecting your home? Simple Insights draw on over 100 years of State Farm knowledge around home insurance claims.

Learn about wind mitigation, possible benefits and discounts on home insurance.

Help maintain the safety of your home by considering these annual home safety tips that cover everything from the the attic to the basement.

Wondering what to store or what not to store in the garage? Some items may surprise you. Learn how to keep your garage safe.

House fires can start in various ways, all resulting in danger. Familiarize yourself with these fire prevention tips to help reduce the risk.
1 2024 Hermes Creative Awards Gold Winner: Mobile App, Mobile Info Experience.
This contains only a general description of available coverages and is not a statement of contract. Coverages are subject to all policy provisions and applicable endorsements. For further information, contact your State Farm agent.